HFEQ
1. Summary
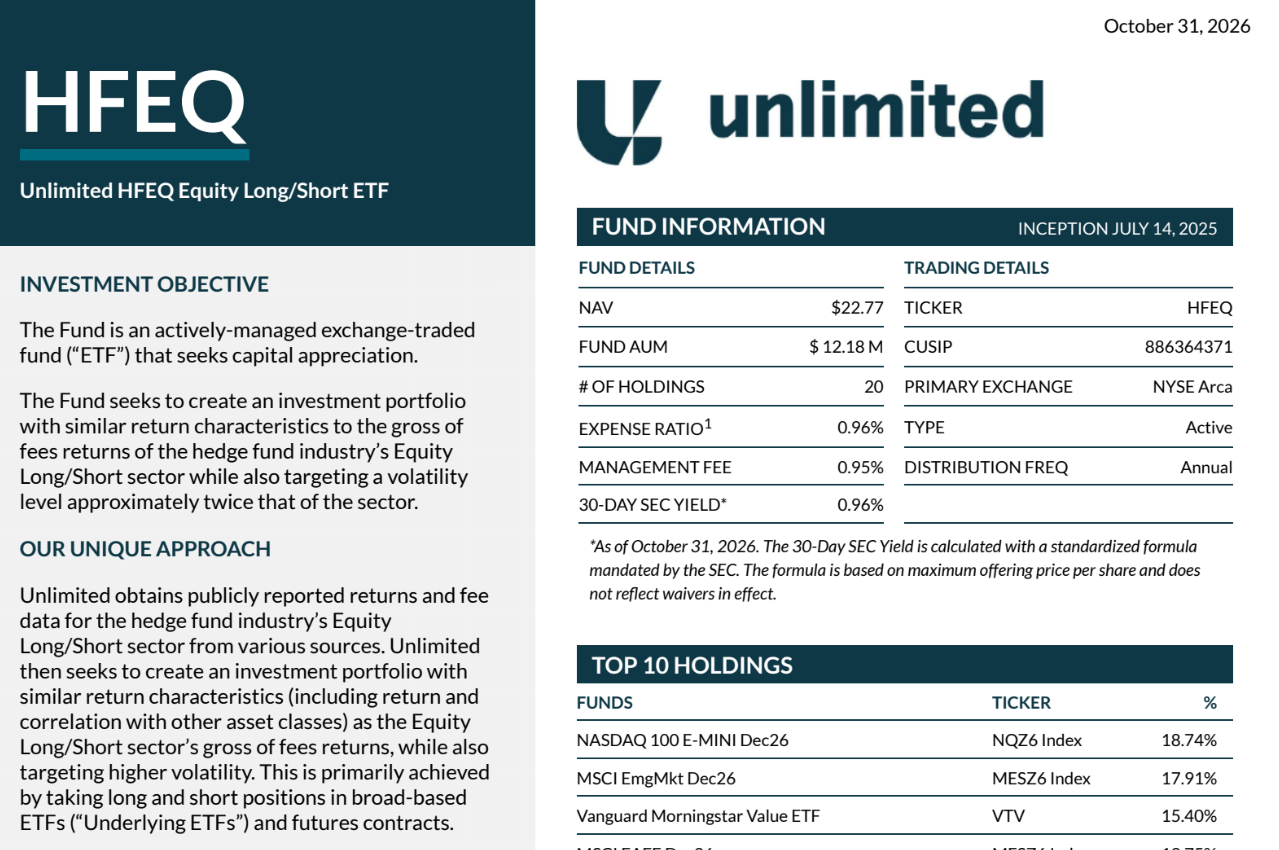
- HFEQ is an actively managed ETF that tries to copy the gross of fees returns of the hedge fund industry's Equity Long/Short sector at about twice that sector's volatility. It does this with 10 to 30 long and short positions in broad ETFs and index futures, picked by a machine learning model.
- The fund documents give no exposure figures. The N-PORT for August 31, 2026 does: long 170.0%, short 4.9%, gross 1.75x and net 165.1% of net assets (my arithmetic). Half the long side is ETFs (85.0%) and half is long equity index futures (85.0%). The only short was one S&P Real Estate sector future. A long VIX future adds 7.3%, for 1.82x gross if counted (my arithmetic). At that date it ran as a leveraged net long fund, not a hedged one (my inference).
- It shorts in two ways: short sales of ETF shares through a broker, and selling index futures. Swaps are allowed and the prospectus says they will be used "to a lesser extent," but none show in the top 10 holdings. At August 31, 2026 it held no ETF short sales and no swaps (HFEQ-NP, Part C).
- Most relevant for us: this is a Tidal-platform fund that gets its extra exposure from index futures, which is one of the paths Tidal named. But it is an ETF and futures replication fund, not a single-stock book, and its gross was 1.75x at August 31, 2026, almost all net long. It gives little direct evidence on running 150/150 in single stocks.
2. Key facts
| Item | Detail | Source |
|---|---|---|
| Name and ticker | Unlimited HFEQ Equity Long/Short ETF (HFEQ) | HFEQ-FS, page 1, header and "Trading Details" |
| Exchange | Conflict. Fact sheet: "PRIMARY EXCHANGE NYSE Arca." Prospectus and SAI covers: "Listed on New York Stock Exchange LLC as of January 2, 2026." The SAI says HFEQ shares are "listed on the New York Stock Exchange LLC" while five other series are on NYSE Arca. The fact sheet is the later document. | HFEQ-FS, page 1, "Trading Details"; HFEQ-PR, page 2, cover; HFEQ-SAI, page 2, cover; HFEQ-SAI, page 4, "General Information about the Trust" |
| CUSIP | 886364371 | HFEQ-FS, page 1, "Trading Details" |
| Inception date | July 14, 2025 | HFEQ-FS, page 1, "Fund Information"; HFEQ-PR, page 86, "Financial Highlights" footnote (a) |
| Trust | Tidal Trust I, a Delaware statutory trust, "an open-end management investment company consisting of multiple series." Named Tidal ETF Trust before June 2, 2025. Tidal served as adviser or sub-adviser for 340 registered funds as of November 30, 2025. So it is a multi-client series trust (my inference). | HFEQ-SAI, page 2, cover; HFEQ-SAI, page 4, "General Information about the Trust"; HFEQ-PR, page 79, "Investment Adviser" |
| Fiscal year end | August 31 (first fiscal period July 14, 2025 to August 31, 2025) | HFEQ-PR, page 86, "Financial Highlights"; HFEQ-SAI, page 48, "Financial Statements" |
| Net assets and NAV | $12.18 million and $22.77 per share (fact sheet dated October 31, 2026). Earlier: $18,890,581.82 at August 31, 2026, and $10,397 thousand and $20.80 per share at August 31, 2025. | HFEQ-FS, page 1, "Fund Details"; HFEQ-NP, Item B.1.c; HFEQ-PR, page 86, "Financial Highlights" |
| Morningstar category and rating | Not stated | |
| Number of long and short positions | 20 holdings in total (fact sheet). Prospectus: "long and short positions in 10-30 Underlying ETFs and futures contracts." The fund documents don't give the split. N-PORT at August 31, 2026: 21 holdings. These are 10 ETFs (all long), 10 index futures (9 long, 1 short) and a money market fund. | HFEQ-FS, page 1, "Fund Details"; HFEQ-PR, page 5, "The Investment Process"; HFEQ-NP, Part C |
| Distribution frequency | Conflict. Fact sheet table: "Annual." Fact sheet note: "The fund intends to pay out dividends and interest income, if any, monthly." Prospectus: dividends and interest income "annually," capital gains "at least annually." | HFEQ-FS, page 1, "Trading Details" and "Performance" notes; HFEQ-PR, page 82, "Dividends and Distributions" |
| Creations and redemptions | In kind and/or cash: "in exchange for a portfolio of securities (the “Deposit Securities”) and/or a designated amount of U.S. cash." Fixed creation and redemption fee $500 each, maximum variable fee 2%. Derivatives may not be redeemable in kind. | HFEQ-PR, page 10, "Purchase and Sale of Shares"; HFEQ-SAI, pages 39 and 40, transaction fee tables; HFEQ-PR, page 7, "Cash Redemption Risk" |
3. Service providers
| Role | Firm | Source |
|---|---|---|
| Adviser | Tidal Investments LLC. It also trades the portfolio and selects broker-dealers. | HFEQ-PR, page 9, "Management"; HFEQ-PR, page 79, "Investment Adviser" |
| Sub-adviser | Unlimited Funds Inc. Founded February 2022; about $177.6 million under management as of November 30, 2025. Address changed by supplement dated May 4, 2026. | HFEQ-PR, page 9, "Management"; HFEQ-PR, page 79, "Investment Sub-Adviser"; HFEQ-PR, page 1, supplement |
| Portfolio managers | Bob Elliott (Chief Investment Officer of the sub-adviser) and Bruce McNevin (Chief Data Scientist), since inception in 2025 | HFEQ-PR, page 9, "Portfolio Managers"; HFEQ-SAI, page 26, "Portfolio Managers" |
| Administrator | Tidal ETF Services LLC, an affiliate of the adviser | HFEQ-SAI, page 29, "Administrator"; HFEQ-PR, page 90, back cover |
| Fund accountant | U.S. Bancorp Fund Services, LLC, doing business as U.S. Bank Global Fund Services. It was also sub-administrator until July 31, 2025. | HFEQ-PR, page 90, back cover; HFEQ-SAI, page 30, "Fund Accountant and Transfer Agent" |
| Custodian | U.S. Bank National Association | HFEQ-SAI, page 31, "Custodian"; HFEQ-PR, page 90, back cover |
| Transfer agent | U.S. Bank Global Fund Services | HFEQ-PR, page 90, back cover; HFEQ-SAI, page 30 |
| Distributor | Foreside Fund Services, LLC | HFEQ-PR, page 85, "Distribution"; HFEQ-SAI, page 28, "The Distributor"; HFEQ-FS, page 2 |
| Auditor | Cohen & Company, Ltd. | HFEQ-SAI, page 31, "Independent Registered Public Accounting Firm"; HFEQ-PR, page 86 |
| Prime broker | Not stated. Short sales go through "a broker." Futures go through an FCM (futures commission merchant, a broker for futures) "that has been selected by the Fund," also not named. The N-PORT lists each future's counterparty as its exchange: Chicago Mercantile Exchange, Cboe Futures Exchange, Eurex and ICE Futures US Indices. It names no FCM or broker. | HFEQ-PR, page 71, "Shorting by Borrowing"; HFEQ-SAI, page 10, futures margin passage; HFEQ-NP, Item C.11.b |
| Swap counterparties | Not stated. Swaps are "entered into primarily with major global financial institutions." No swaps held at August 31, 2026. | HFEQ-PR, page 71, "Additional Information about the Funds"; HFEQ-NP, Part C |
| Securities lending agent | Not stated. "The Funds did not participate in securities lending for the fiscal period ended August 31, 2025." No securities on loan at August 31, 2026. | HFEQ-SAI, page 14, "Securities Lending"; HFEQ-NP, Items B.4 and C.12 |
4. Strategy
- Objective and benchmark. The fund "seeks capital appreciation" (HFEQ-PR, page 4, "Investment Objective"). It aims for returns like the "gross of fees returns of the hedge fund industry’s Equity Long/Short sector" while "targeting a volatility level approximately twice that of the sector" (HFEQ-PR, page 4, "Principal Investment Strategies"). No hedge fund index is named. The fact sheet compares returns with the S&P 500 (HFEQ-FS, page 1, "Performance").
- Universe. Mostly passive ETFs: sector ETFs, factor ETFs (such as value and momentum), and U.S., developed, emerging and single-country ETFs (HFEQ-PR, page 5, "Portfolio Construction"). It also uses exchange-listed futures. At least 80% of net assets go to equity securities, equity ETFs and equity index futures (HFEQ-PR, page 6). The top 10 holdings on October 31, 2026 include futures on the Nasdaq 100, MSCI Emerging Markets, MSCI EAFE, S&P 500 and EURO STOXX 50 (HFEQ-FS, page 1, "Top 10 Holdings").
- How it picks positions. Quantitative. The sub-adviser reads publicly reported hedge fund sector returns, then uses "a proprietary algorithm" to find the mix of ETFs and futures that best matches recent sector returns "while approximately doubling its volatility" (HFEQ-PR, page 5, "The Investment Process"). Portfolio managers choose which return factors go into the model (HFEQ-PR, page 5). The prospectus says the machine learning models "have not formed the basis of actual investments by the Sub-Adviser" as of its date (HFEQ-PR, page 6, "Machine Learning, Model and Data Risk").
- Neutrality targets. None stated. It takes "directionally similar positions as the hedge fund industry Equity Long/Short sector with larger notional exposure" (HFEQ-PR, page 5). It is not built to be beta, dollar or sector neutral (my inference).
- Net exposure. No target or range is stated.
- Limits on position size. No numeric limit. The fund is non-diversified (HFEQ-PR, page 6). Fundamental policy bars holding "more than 25% of its total assets" in one industry (HFEQ-SAI, page 15, "Investment Restrictions"). The largest holding on October 31, 2026 was the Nasdaq 100 E-mini future at 18.74% (HFEQ-FS, page 1).
5. Exposure and leverage
- Measured exposure, August 31, 2026 (HFEQ-NP, Part C). Net assets $18,890,581.82 (Item B.1.c). Futures are counted at notional on the trade date plus unrealized gain or loss (my arithmetic).
| Position | Direction | Value or notional | % of net assets |
|---|---|---|---|
| 10 ETFs: Vanguard Morningstar Value, Vanguard Morningstar Mid-Cap, State Street Materials, Industrial, Consumer Discretionary, Utilities and Energy Select Sector SPDRs, SPDR S&P Retail, SPDR S&P Biotech, Vanguard US Momentum Factor | Long | $16,062,400.69 | 85.0% |
| Nasdaq 100 E-mini, 6 contracts | Long | $3,541,560 | 18.7% |
| MSCI Emerging Markets, 30 contracts | Long | $2,566,650 | 13.6% |
| MSCI EAFE, 15 contracts | Long | $2,421,600 | 12.8% |
| EURO STOXX 50, 32 contracts | Long | $2,392,714 | 12.7% |
| S&P 500 E-mini, 5 contracts | Long | $1,924,750 | 10.2% |
| Russell 2000 E-mini, 10 contracts | Long | $1,479,350 | 7.8% |
| Financial Select Sector, 6 contracts | Long | $1,067,295 | 5.6% |
| Nikkei 225 (CME), 2 contracts | Long | $659,100 | 3.5% |
| S&P Real Estate Select Sector, 17 contracts | Short | $918,425 | 4.9% |
| Cboe VIX, 83 contracts | Long | $1,374,505 | 7.3% |
| First American Government Obligations Fund | Long | $1,149,741.19 | 6.1% |
| Cash (Item B.2.f) | $1,770,099.84 | 9.4% |
- Long: 85.0% ETFs plus 85.0% equity index futures is 170.0% (my arithmetic).
- Short: 4.9% (my arithmetic). No ETF short sales.
- Gross 174.9%, or 1.75x. Net 165.1% (my arithmetic).
- The VIX future is long volatility, which tends to gain when stocks fall. It is left out of the long figure. Counting it adds 7.3% and gives 1.82x gross (my arithmetic).
- The EURO STOXX 50 notional is reported in euros (EUR 2,019,473.37). It is converted at the N-PORT's exchange rate of 0.86088, read as euros per dollar (my inference).
- All futures are September 2026 contracts.
- Fact sheet, October 31, 2026. The fact sheet shows only the top 10 holdings, all with positive weights, as of October 31, 2026 (HFEQ-FS, page 1, "Top 10 Holdings"). It does not say whether futures weights are notional or what base the percentages use.
- Top 10 total: 116.05% (my arithmetic).
- Five index futures: 68.65% (my arithmetic).
- Five ETFs: 47.40% (my arithmetic).
- So long exposure is at least about 116% of net assets, if the weights are notional percents of net assets (my inference). Short positions, if any, are not shown.
- The fact sheet's futures weights look like notional percents of net assets (my inference). In the N-PORT each future's market value is its unrealized gain or loss, under 1% of net assets, while its notional runs from 3.5% to 18.7% (HFEQ-NP, Part C). The fact sheet's futures weights of 6.75% to 18.74% only fit notional. The dates and contract months differ (September 2026 contracts in the N-PORT, December 2026 on the fact sheet), and the single weights moved a lot: MSCI Emerging Markets 13.6% then 17.91%, EURO STOXX 50 12.7% then 6.75%.
- Stated targets or limits. None for long, short, gross or net exposure. The only target is volatility at about twice the Equity Long/Short sector (HFEQ-PR, page 4).
- How it gets exposure above 100%. Futures: "The use of futures contracts will allow the Fund to take the larger notional economic exposure needed to achieve the higher target volatility" (HFEQ-PR, page 6, "Principal Investment Strategies"). And: "To seek to achieve the Fund’s target volatility level, the Fund will use futures contracts and, to a lesser extent, swaps" (HFEQ-PR, page 5, "Portfolio Construction"). Reinvesting short sale proceeds is not described.
- Borrowing limits. HFEQ is not among the funds that borrow for investment. "Although the Funds (other than the Unlimited HFND Multi-Strategy Return Tracker ETF and the Unlimited Ultra HFND Multi-Strategy ETF) do not intend to borrow money, a Fund may do so to the extent permitted by the 1940 Act." Each fund "may borrow up to one-third (1/3) of its total assets" (HFEQ-SAI, page 6, "Borrowing"). One-third of total assets equals 300% asset coverage (my inference). No line of credit is named. The SAI mentions one only as a possible cost (HFEQ-SAI, page 6).
- Hedge fund comparison. The prospectus says "hedge funds may use more leverage than the Fund" (HFEQ-PR, page 5, "What the Fund will NOT do").
6. Shorting, financing and collateral
- How it shorts. A mix:
- Short sales of ETF shares: "the Fund will also “short” the securities of Underlying ETFs" (HFEQ-PR, page 6, "Principal Investment Strategies"). The method: "a Fund will arrange through a broker to borrow the security it does not own" (HFEQ-PR, page 71, "Shorting by Borrowing").
- Short futures: "the Funds may effect shorting by selling futures contracts on either large-cap equity securities or indices" (HFEQ-PR, page 71, "Shorting by Futures Contracts").
- The share of each method is not given. At August 31, 2026 the only short was 17 S&P Real Estate Select Sector futures, 4.9% of net assets. There were no ETF short sales (HFEQ-NP, Part C) (my arithmetic).
- Who lends the stock and who holds collateral. An unnamed broker. "the broker effecting the short sale typically holds the proceeds as part of the collateral securing the Fund’s obligation to cover the short position" (HFEQ-PR, page 71). "A Fund will be required to pledge its liquid assets to the broker to secure its performance on short sales" (HFEQ-SAI, page 14, "Short Sales").
- Futures margin. Initial margin goes to "an account controlled by the FCM (that has been selected by the Fund)." Variation margin "is monitored by the Adviser and Custodian (defined below) on a daily basis" (HFEQ-SAI, page 10). The SAI warns FCM assets sit "in an omnibus account with assets belonging to the FCM’s other customers" (HFEQ-SAI, page 10).
- What is posted. Short sale proceeds plus "liquid assets" (HFEQ-PR, page 71; HFEQ-SAI, page 14). Whether long ETF shares are pledged is not stated.
- Short sale proceeds used to buy longs. Not stated.
- Segregated or tri-party account. The SAI says a fund "must segregate assets determined to be liquid in accordance with procedures established by the Board, or otherwise cover its positions in a permissible manner" (HFEQ-SAI, page 14). No tri-party or special custody account is named.
- Costs named. Short sales may bring "costs of borrowing and margin account maintenance costs." "Dividend expenses on securities sold short will be borne by the shareholders of the Funds" (HFEQ-SAI, page 14). The margin type (Reg T or portfolio margin) is not stated.
- Swaps. Principal strategy says the fund "will use futures contracts and, to a lesser extent, swaps" (HFEQ-PR, page 5). It "can also invest in swap agreements for similar purposes" (HFEQ-PR, page 6). No swap type, counterparty or swap holding is named, and none appears in the top 10 (HFEQ-FS, page 1). The N-PORT shows no swaps at August 31, 2026; every derivative is a future (HFEQ-NP, Item C.11.a). I left swaps out of Leverage Method for that reason (my inference).
- Permitted only. Individual stocks: "the Fund may invest in long or short positions of equity securities and swap agreements" if ETFs can't build the target portfolio (HFEQ-PR, page 5). Options and futures are carved out of the commodities restriction (HFEQ-SAI, page 15).
- No Cayman subsidiary. HFEQ is not among the funds that use a Cayman subsidiary (HFEQ-PR, page 71; HFEQ-PR, page 73, risk table leaves HFEQ unmarked for Cayman Subsidiary Risk). Oddly, its financial highlights are titled "Consolidated Financial Highlights" (HFEQ-PR, page 86).
- Securities lending. Permitted, but the funds "did not participate in securities lending for the fiscal period ended August 31, 2025" (HFEQ-SAI, page 14). None at August 31, 2026 either (HFEQ-NP, Items B.4 and C.12).
- Cash and borrowing, August 31, 2026. Cash of $1,770,099.84 (9.4%) and a government money market fund of $1,149,741.19 (6.1%), together 15.5% of net assets (HFEQ-NP, Item B.2.f and Part C) (my arithmetic). This cash likely backs futures margin (my inference). Borrowings were zero (HFEQ-NP, Item B.2.c).
7. Derivatives and Rule 18f-4
- Derivatives used. Index futures as the main tool (HFEQ-PR, pages 5 and 6; HFEQ-FS, page 1). Swaps to a lesser extent (HFEQ-PR, page 5). The prospectus expects "futures on equity indexes, commodities, credit, currency, and fixed income" across the series, and swaps "referencing the same indexes as futures" (HFEQ-PR, page 71). At August 31, 2026: 10 futures on equity indexes and the VIX, and nothing else (HFEQ-NP, Part C).
- Limited derivatives user or full program. Full program: "The Funds have implemented a derivatives risk management program that complies with Rule 18f-4" (HFEQ-SAI, page 9). So HFEQ is not run as a limited derivatives user (my inference). The derivatives risk manager is not named. The N-PORT leaves Item B.9 (limited derivatives users) blank, which fits a full program (HFEQ-NP, Item B.9) (my inference).
- VaR test and reference portfolio. The SAI says only that "a fund’s derivatives exposure is limited through a value-at-risk test" (HFEQ-SAI, page 9). The N-PORT names the test: relative VaR, with the S&P 500 Total Return Index (SPTR) as the designated index (HFEQ-NP, Item B.10.b). The median VaR and VaR ratio fields are blank in this copy (HFEQ-NP, Item B.10).
- Commodity pool status (CFTC Rule 4.5). "With regard to the Funds (but not the Subsidiary (defined below)), the Adviser claims relief from the definition of commodity pool operator" under Rule 4.5 (HFEQ-SAI, page 9). HFEQ has no subsidiary, so the exclusion covers it (my inference).
8. Costs
| Item | Amount | Source |
|---|---|---|
| Management fee | 0.95%. Unitary: the adviser pays all fund expenses except Excluded Expenses. | HFEQ-PR, page 4, "Fees and Expenses of the Fund"; HFEQ-PR, page 79, "Investment Adviser" |
| Other expenses | 0.00% | HFEQ-PR, page 4 |
| Dividend and interest expense on short sales | Not stated as an amount. Excluded from the unitary fee and paid by the fund. | HFEQ-PR, page 4, footnote 1; HFEQ-SAI, page 14 |
| Borrowing costs | Not stated as an amount. "interest charges on any borrowings" are Excluded Expenses. | HFEQ-PR, page 4, footnote 1 |
| Acquired fund fees | 0.01% | HFEQ-PR, page 4; HFEQ-FS, page 2, footnote 1 |
| Gross and net expense ratio | 0.96% and 0.96%. No waiver line. Actual ratio for July 14 to August 31, 2025: 0.95%, annualized, excluding underlying ETF expenses. | HFEQ-PR, page 4; HFEQ-FS, page 1; HFEQ-PR, page 86, "Financial Highlights" footnotes (f) and (h) |
| Fee waivers or caps | None stated | HFEQ-PR, page 4 |
| Stated financing spreads or rates | Not stated | |
| Where financing costs are reported | Not stated. Short dividends and interest are Excluded Expenses with no line in the fee table. Futures financing is built into futures prices and shows up in returns, not expenses (my inference). | HFEQ-PR, page 4, footnote 1 |
- Who pays what. The fund pays the 0.95% unitary fee plus Excluded Expenses: interest on borrowings, dividends and other expenses on short sales, taxes, brokerage commissions, acquired fund fees, deferred tax, 12b-1 fees, litigation and extraordinary costs (HFEQ-PR, page 79). The adviser pays the sub-adviser 0.02% of net assets. The sub-adviser "has agreed to assume the Adviser’s obligation to pay all expenses incurred by the Funds" apart from fees and Excluded Expenses, and receives "the profits, if any, generated by each Fund’s unitary management fees" (HFEQ-PR, page 80, "Investment Sub-Adviser").
- Fees paid, July 14 to August 31, 2025. Management fee $5,572 (HFEQ-SAI, page 25); sub-advisory fee $9 (HFEQ-SAI, page 26); administrator $1,863 (HFEQ-SAI, page 30); Global Fund Services $1,281 (HFEQ-SAI, page 30).
- 12b-1 plan. Up to 0.25%, but "No payments pursuant to the Plan are expected to be made during the twelve (12) month period from the date of this SAI" (HFEQ-SAI, page 29). Fee table shows 0.00% (HFEQ-PR, page 4).
- Expense example. $98 for 1 year and $306 for 3 years per $10,000 (HFEQ-PR, page 4).
- Brokerage commissions and turnover. $1,172 in commissions and 125% turnover for July 14 to August 31, 2025 (HFEQ-SAI, page 33, "Brokerage Transactions"; HFEQ-SAI, page 35, "Portfolio Turnover Rate"; HFEQ-PR, page 4). Turnover excludes in-kind transactions (HFEQ-PR, page 86, footnote (i)). No later year is given.
- Gap between expense ratio and management fee. 0.96% minus 0.95% is 0.01% (my arithmetic). The fact sheet explains it: "If Acquired Fund Fees and Expenses were excluded, the Expense Ratio would be 0.95%" (HFEQ-FS, page 2, "Notes and Important Information"). The first period's actual ratio of 0.95% equals the management fee, so short dividends and interest were below 0.005% that period, or zero (my inference).
9. Performance and risk
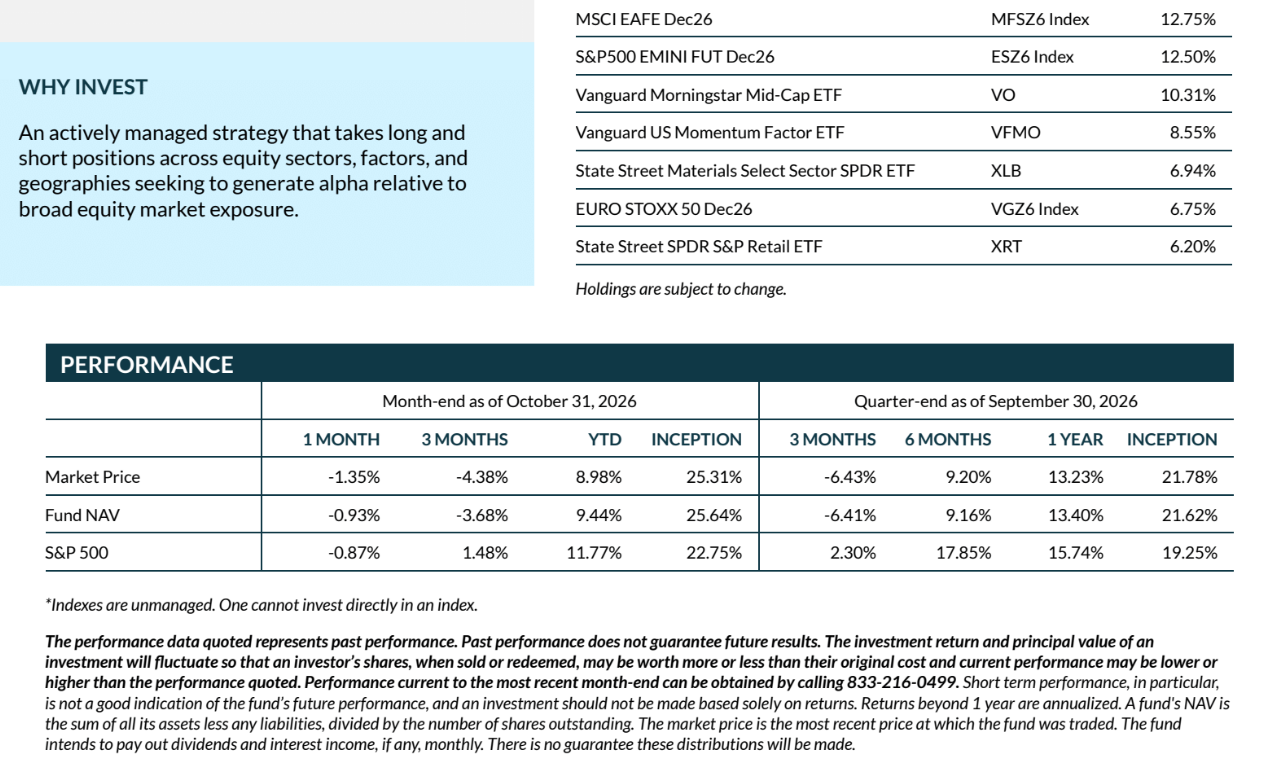
Fact sheet returns (HFEQ-FS, page 1, "Performance"). The fact sheet says "Returns beyond 1 year are annualized," so the since-inception figures are annualized (my inference, since inception was July 14, 2025).
| Period | NAV | Market price | S&P 500 |
|---|---|---|---|
| 1 month to Oct 31, 2026 | -0.93% | -1.35% | -0.87% |
| 3 months to Oct 31, 2026 | -3.68% | -4.38% | 1.48% |
| YTD to Oct 31, 2026 | 9.44% | 8.98% | 11.77% |
| Since inception to Oct 31, 2026 | 25.64% | 25.31% | 22.75% |
| 3 months to Sep 30, 2026 | -6.41% | -6.43% | 2.30% |
| 6 months to Sep 30, 2026 | 9.16% | 9.20% | 17.85% |
| 1 year to Sep 30, 2026 | 13.40% | 13.23% | 15.74% |
| Since inception to Sep 30, 2026 | 21.62% | 21.78% | 19.25% |
- First fiscal period. Total return 3.98%, not annualized, July 14 to August 31, 2025 (HFEQ-PR, page 86, "Financial Highlights").
- Calendar-year returns. None. The prospectus has no performance chart because the fund "has not completed a full calendar year of operations as of the date of this Prospectus" (HFEQ-PR, page 9, "Performance").
- Risk statistics. None given (no beta, correlation, volatility, Sharpe ratio, drawdown or capture figures).
- Benchmark gap. The fact sheet compares with the S&P 500, not with a hedge fund index (HFEQ-FS, page 1). The fund's target is an Equity Long/Short hedge fund sector at twice its volatility (HFEQ-PR, page 4).
10. History and structural changes
- Predecessor funds. None stated. It started with NAV of $20.00 on July 14, 2025 (HFEQ-PR, page 86).
- Reorganizations and 351 conversions. None. Section 351 appears only in a rule letting the trust reject creation orders that would give a buyer "80% or more of the outstanding Shares" (HFEQ-SAI, page 45, "Federal Income Taxes").
- Trust name change. "Prior to June 2, 2025, the Trust was named Tidal ETF Trust" (HFEQ-SAI, page 4).
- Exchange change. The covers say "Listed on New York Stock Exchange LLC as of January 2, 2026" (HFEQ-PR, page 2; HFEQ-SAI, page 2). The documents don't name the earlier exchange. The October 31, 2026 fact sheet still says NYSE Arca (HFEQ-FS, page 1). This conflict is unresolved.
- Sub-adviser address. Changed to 250 Broadway, 29th Floor, New York, by supplement dated May 4, 2026 (HFEQ-PR, page 1; HFEQ-SAI, page 1). The prospectus back cover still shows the old 222 Broadway address (HFEQ-PR, page 90).
- Document dates. Prospectus and SAI dated January 1, 2026, with the May 4, 2026 supplement bound in front. Both predate the fiscal year ended August 31, 2026 and the October 31, 2026 fact sheet. No annual report for fiscal 2026 was attached. The N-PORT reports the fiscal year end, August 31, 2026, and was signed October 26, 2026 (HFEQ-NP, Item A.3 and signature block).
- Fall in net assets. $18,890,581.82 at August 31, 2026 (HFEQ-NP, Item B.1.c) versus $12.18 million at October 31, 2026 (HFEQ-FS, page 1). That is a drop of about 36% in two months (my arithmetic). The documents don't explain it.
- Other conflicts between documents.
- Distribution frequency: annual versus monthly (see section 2).
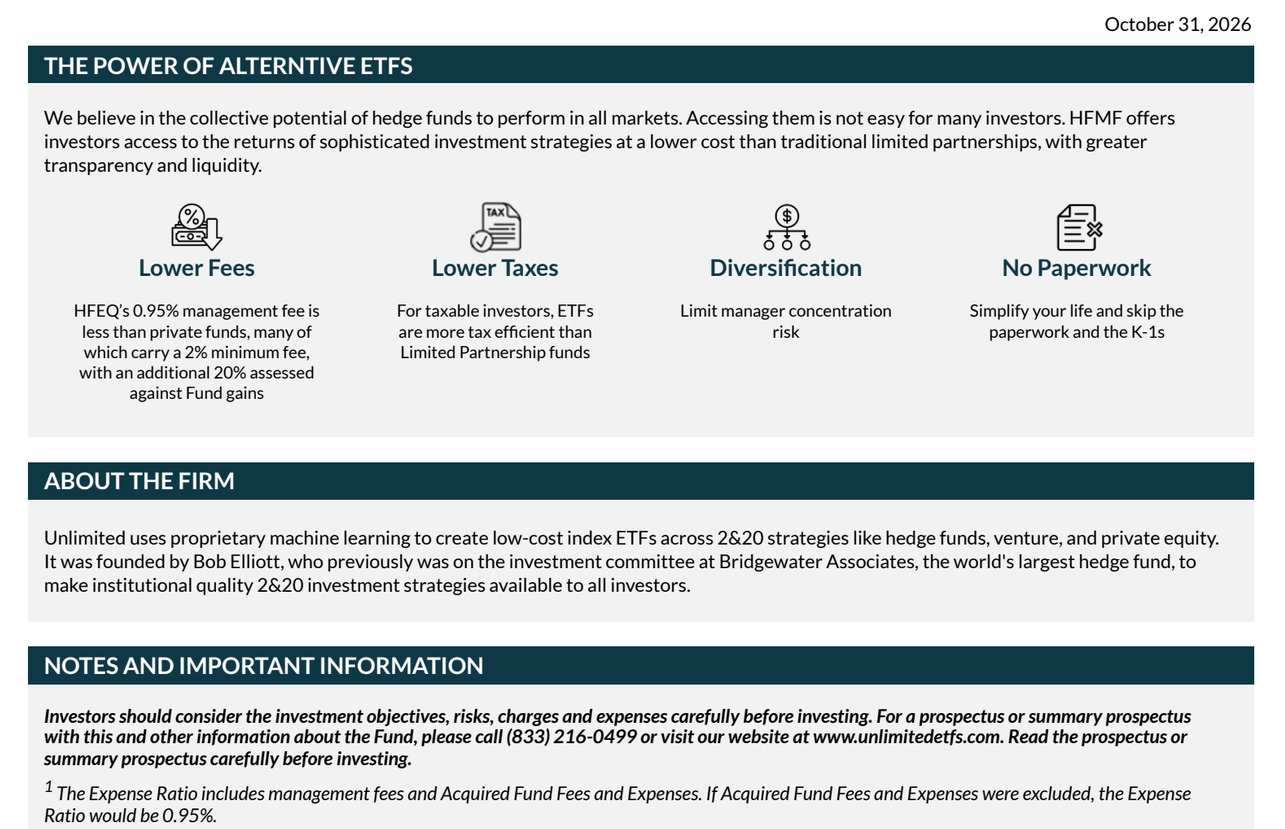
- Fact sheet page 2 says "HFMF offers investors access to the returns of sophisticated investment strategies," naming a different series (HFEQ-FS, page 2, "The Power of Alterntive ETFs"). This looks like a template error (my inference).
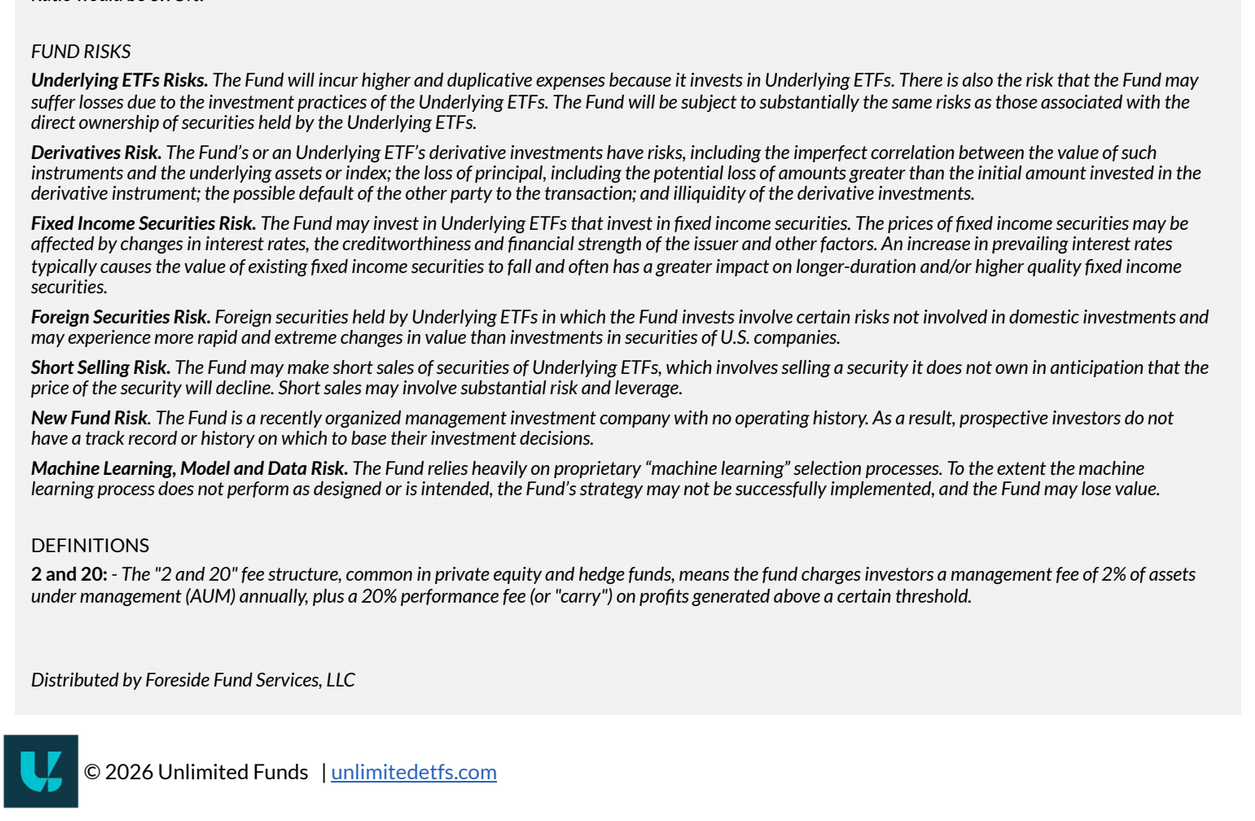
- New fund status: the fact sheet says "no operating history" (HFEQ-FS, page 2, "New Fund Risk"). The prospectus says "a limited operating history" (HFEQ-PR, page 9, "Newer Fund Risk").
- Fixed income risk: the fact sheet lists "Fixed Income Securities Risk" (HFEQ-FS, page 2). The prospectus summary does not, and the risk table leaves HFEQ unmarked for Fixed Income Risk (HFEQ-PR, page 73).
11. Principal risks
Summary list: HFEQ-PR, pages 6 to 9, "Principal Investment Risks". Fund-by-fund table: HFEQ-PR, page 73. Longer descriptions: HFEQ-PR, pages 74 to 78.
- Underlying ETFs Risks (page 6).
- Management Risk (page 6).
- Machine Learning, Model and Data Risk (page 6).
- Data Lag Risk (page 6).
- Equity Market Risk (page 7).
- Volatility Risk (page 7). Flag: leverage. Futures and swaps "may amplify the effects of volatility."
- Derivatives Risk (page 7). Flags: leverage and counterparties. It names "the possible default of the other party to the transaction" and says derivatives "may give rise to a form of leverage."
- Emerging Markets Risk (page 7).
- ETF Risk (pages 7 and 8): Authorized Participants, Market Makers, and Liquidity Providers Concentration Risk; Cash Redemption Risk (flag: derivatives may not be redeemable in kind); Costs of Buying or Selling Shares; Shares May Trade at Prices Other Than NAV; Trading.
- Factor Risk (page 8).
- Foreign Securities Risk (page 8).
- Futures Contracts Risk (page 8). Flag: leverage and financing. Losses "may be unlimited," daily margin calls, and roll cost when futures are in "contango."
- General Market Risk (page 8).
- High Portfolio Turnover Risk (page 8).
- Market Capitalization Risk: large, mid and small cap (pages 8 and 9).
- Newer Fund Risk (page 9).
- Non-Diversification Risk (page 9).
- Recent Market Events Risk (page 9).
- Sector Risk (page 9).
- Short Selling Risk (page 9). Flag: shorting. "Short sales may involve substantial risk and leverage." Losses "may be unlimited."
- Swap Agreement Risk (page 9). Flag: counterparties. Swaps "are also subject to counterparty risk."
The risk table also marks HFEQ for High Yield Securities Risk, which is not in its summary list (HFEQ-PR, page 73). The table does not mark HFEQ for Leveraging Risk (HFEQ-PR, page 73). No principal risk names the prime broker, the FCM, or borrow recalls.
12. Relevance to our fund
- How close is its structure and leverage? Not close (my inference). It shares the platform (Tidal), the 40 Act ETF wrapper, the unitary fee model and the custodian. But it holds 10 to 30 ETFs and index futures, not 150 single stocks. It has no market neutral target and no stated gross level.
- What does it show about 3.0x gross in a 40 Act ETF? (my inference)
- It is a live example of the futures path Tidal named on our call (S2, S12 in
fund_context.md). Index futures carry the extra long exposure. At August 31, 2026 they took the long side from 85.0% to 170.0% of net assets, at 1.75x gross (HFEQ-NP, Part C) (my arithmetic). - It shows nothing about direct single-stock shorting above 2.0x. Its direct shorts are on ETF shares, the margin type is not stated, and it held none at August 31, 2026 (HFEQ-NP, Part C).
- Futures on broad indexes can't build a single-stock market neutral book. They could only add or hedge market or sector exposure on top of one. For our fund, futures might hedge beta, but the 150/150 stock books still need direct shorts or swaps.
- It is a live example of the futures path Tidal named on our call (S2, S12 in
- What does it show about financing, collateral, custody and costs? (my inference)
- Custody: U.S. Bank is custodian. Futures margin sits at an unnamed FCM in an omnibus account, and short collateral sits with an unnamed broker. This matches Tidal's statement that shorts are held away from the main custodian.
- Costs: like other Tidal funds, short dividends, borrow costs and interest are Excluded Expenses outside the 0.95% unitary fee. The first period's 0.95% actual ratio suggests short costs were near zero then.
- Futures financing is built into futures prices and never appears as an expense. So a futures-based fund's expense ratio understates its true financing cost. This is the same trap as hidden swap costs in
fund_context.md. Tidal also flagged futures margin and roll costs (O6, O7), and the prospectus names roll cost in contango (HFEQ-PR, page 8). - The leverage cost formulas in
fund_context.mdhave no futures row. HFEQ can't be scored on them from these documents. - Economics: the sub-adviser sponsors the fund, pays its expenses from the unitary fee and keeps the profit. This is the same sponsor model seen elsewhere on Tidal.
13. Gaps and open questions
What the documents don't answer, for a 150/150 fund:
- Long, short, gross and net exposure at any date other than August 31, 2026 (see section 5).
- Whether the fact sheet weights are notional. The N-PORT points to yes (see section 5), but the fact sheet doesn't say.
- How often the fund uses ETF short sales or swaps. Neither was held at August 31, 2026 (HFEQ-NP, Part C).
- The broker that lends ETF shares, the FCM, any swap counterparty, and the margin type (Reg T or portfolio margin).
- Whether short sale proceeds buy longs, and whether long ETF shares are pledged.
- Short dividend, borrow fee, margin interest and futures financing figures for the fiscal year ended August 31, 2026. That annual report wasn't attached.
- The derivatives risk manager and the median VaR figures. The VaR test is relative, against the S&P 500 Total Return Index (HFEQ-NP, Item B.10.b).
- Why net assets fell from $18.89 million at August 31, 2026 to $12.18 million at October 31, 2026.
- Beta and other risk statistics.
- Which exchange it lists on now.
Questions to ask:
- To the fund: What were long, short and gross exposure on October 31, 2026? Are the futures weights notional?
- To the fund: How much of the short book is ETF short sales versus short futures? Who lends the ETF shares, and is it a Reg T or portfolio margin account?
- To Tidal: What median VaR ratio to the S&P 500 Total Return Index has HFEQ run? How high has its derivatives exposure run?
- To the fund: Does it short ETF shares at all in practice? None were short at August 31, 2026.
- To Tidal: Could a 150/150 single-stock fund use index futures to hedge beta while keeping stock books at about 100/100? How would that count under Rule 18f-4?
- To the fund: What did futures roll and implied financing cost in fiscal 2026?
- To the fund: Is HFEQ listed on NYSE or NYSE Arca? Does it distribute monthly or annually?
Search terms tried for fields left "Not stated":
- Exposure and gross: leverage, notional, long, short, gross, net exposure, borrowings.
- Prime broker and margin type: prime broker, borrow, margin, Regulation T, portfolio margin, counterpart, futures commission, FCM, pledge, segregat.
- Leverage cost and short dividends: short sale, sold short, dividend, interest, borrowing, asset coverage, line of credit, swap, box spread, reverse repurchase.
- VaR test: 18f-4, value at risk, derivatives risk manager, limited derivatives user.
- Securities lending agent: securities lending, lend portfolio.
- Beta and Morningstar: beta, Morningstar, volatility.
- Predecessor and conversions: predecessor, reorganiz, 351.
- Other: CUSIP (not in prospectus or SAI), Arca, fiscal year, Rule 4.5, commodity pool, Subsidiary, Cayman.
14. Documents used
| Code | Document | Date | Pages | Pages read | File name |
|---|---|---|---|---|---|
| HFEQ-FS | Fact sheet, supplied as four page images (two per page) | October 31, 2026 (returns to October 31 and September 30, 2026) | 2 | 1 and 2 (all, from images) | b00fd232-image.png and e5bbf635-image.png (page 1); a7a3cf1d-image.png and f65f993b-image.png (page 2). Sender's names: HFEQ_fact_sheet_pg_1_pt_1.png, HFEQ_fact_sheet_pg_1_pt_2.png, HFEQ_fact_sheet_pg_2_pt_1.png, HFEQ_fact_sheet_pg_2_pt_2.png |
| HFEQ-PR | Prospectus for nine Unlimited ETFs, with supplement dated May 4, 2026 bound in front | Prospectus January 1, 2026; supplement May 4, 2026 | 90 | In full: 1 to 10, 71 to 73, 86, 90. Keyword passages only: 74, 75, 77 to 85. | ac61032f-HFEQ_prospectus.pdf |
| HFEQ-SAI | Statement of Additional Information for the same nine ETFs, with the same May 4, 2026 supplement bound in front | SAI January 1, 2026; supplement May 4, 2026 | 48 | In full: 1 to 4, 6, 9, 14. Keyword passages only: 10 to 12, 15, 16, 22, 24 to 31, 33 to 35, 39, 40, 43, 45, 48. | f718ecc6-HFEQ_SAI.pdf |
| HFEQ-NP | Form N-PORT-P, monthly portfolio report, Tidal Trust I, series Unlimited HFEQ Equity Long/Short ETF (S000082853) | Report date August 31, 2026; signed October 26, 2026 | Text file, no pages | Items A.1 to A.3, B.1, B.2, B.4, B.9, B.10, Part C (all 21 holdings), Part E and signature block | 2ff73116-attachment.txt |
Page numbering.
- HFEQ-FS: no printed page numbers. Page 1 is the first two images; page 2 is the last two.
- HFEQ-PR: PDF page 1 is the supplement, PDF page 2 the cover, PDF page 3 the contents (no printed numbers). From PDF page 4 on, PDF page = printed page + 3. HFEQ's own summary is PDF pages 4 to 10 (printed 1 to 7). PDF pages 11 to 70 cover the other eight funds and were not read. Shared sections start at PDF page 71 (printed 68).
- HFEQ-SAI: PDF page 1 is the supplement, PDF page 2 the cover, PDF page 3 the contents. From PDF page 4 on, PDF page = printed page + 3. The SAI covers all nine funds; only shared or HFEQ-specific passages were used.
- HFEQ-NP: text copy with no page numbers. Cited by item number.
15. Snapshot sources
- Ticker: HFEQ-FS, page 1, header and "Trading Details".
- Fund name: HFEQ-FS, page 1, header. Same in HFEQ-PR, page 2, cover.
- As of date: date printed at top of HFEQ-FS, pages 1 and 2. The 30-day SEC yield note also says "As of October 31, 2026" (HFEQ-FS, page 1).
- Adviser: "Tidal Investments LLC serves as investment adviser to the Fund" (HFEQ-PR, page 9, "Management").
- Platform: Tidal is the adviser, and the fund is a series "of Tidal Trust I (formerly, Tidal ETF Trust)" (HFEQ-SAI, page 2, cover).
- Exchange: "PRIMARY EXCHANGE NYSE Arca" (HFEQ-FS, page 1, "Trading Details") versus "Listed on New York Stock Exchange LLC as of January 2, 2026" (HFEQ-PR, page 2, cover; HFEQ-SAI, page 2, cover). Conflict left unresolved.
- Inception: "INCEPTION JULY 14, 2025" (HFEQ-FS, page 1, "Fund Information").
- Net assets: "FUND AUM $ 12.18 M" (HFEQ-FS, page 1, "Fund Details"), fact sheet dated October 31, 2026.
- Strategy type: (my inference) from the fund name and the aim to match "the gross of fees returns of the hedge fund industry’s Equity Long/Short sector" (HFEQ-PR, page 4, "Principal Investment Strategies"). No neutrality target is stated, so not Equity market neutral.
- Long %: ETFs of $16,062,400.69 (85.0%) plus eight long equity index futures at $16,053,019 (85.0%) is 170.0% of net assets of $18,890,581.82 (my arithmetic, from HFEQ-NP, Item B.1.c and Part C), as of August 31, 2026. Futures are at notional on the trade date plus unrealized gain or loss. The long VIX future ($1,374,505, 7.3%) is not counted. The fact sheet lists only the top 10 holdings, totaling 116.05% at October 31, 2026 (HFEQ-FS, page 1, "Top 10 Holdings").
- Short %: 17 S&P Real Estate Select Sector futures sold, $918,425 (4.9%) (my arithmetic, from HFEQ-NP, Part C), as of August 31, 2026. No other short position.
- Gross: 170.0% plus 4.9% is 174.9%, or 1.75x; 182.1%, or 1.82x, counting the VIX future (my arithmetic), as of August 31, 2026.
- Above 2.0x: No, from the gross figure above.
- Net: 170.0% minus 4.9% is 165.1% (my arithmetic), as of August 31, 2026.
- Short method: "taking long and short positions in broad-based ETFs (“Underlying ETFs”) and futures contracts" (HFEQ-PR, page 5, "Principal Investment Strategies"); "Shorting by Borrowing" and "Shorting by Futures Contracts" (HFEQ-PR, page 71).
- Prime broker or counterparty: the documents say only "a broker" (HFEQ-PR, page 71) and "the FCM (that has been selected by the Fund)" (HFEQ-SAI, page 10). No firm is named. The N-PORT gives each future's exchange as counterparty: "Chicago Mercantile Exchange", "Cboe Futures Exchange", "Eurex" and "ICE Futures US Indices" (HFEQ-NP, Item C.11.b), as of August 31, 2026.
- Custodian: HFEQ-SAI, page 31, "Custodian"; HFEQ-PR, page 90, back cover.
- Management fee: HFEQ-PR, page 4, "Fees and Expenses of the Fund"; HFEQ-FS, page 1, "Fund Details". Unitary (HFEQ-PR, page 79).
- Total expense ratio: "Total Annual Fund Operating Expenses 0.96%" (HFEQ-PR, page 4); "EXPENSE RATIO 0.96%" (HFEQ-FS, page 1). No waiver.
- Short costs in expense ratio: the unitary fee excludes "interest charges on any borrowings, dividends and other expenses on securities sold short" (HFEQ-PR, page 4, footnote 1). The fee table has no line for them.
- 3-month return: -3.68% at NAV, 3 months to October 31, 2026 (HFEQ-FS, page 1, "Performance", "Month-end as of October 31, 2026"). The fact sheet also gives -6.41% at NAV for 3 months to September 30, 2026.
- 1-year return: 13.40% at NAV, 1 year to September 30, 2026 (HFEQ-FS, page 1, "Performance", "Quarter-end as of September 30, 2026").
- Beta: not given in any of the three documents.
- Beta benchmark: not stated, because no beta is given.
- Beta period: not stated, because no beta is given.
- Leverage Method:
- Index futures and options: "The use of futures contracts will allow the Fund to take the larger notional economic exposure needed to achieve the higher target volatility" (HFEQ-PR, page 6). Holdings include "NASDAQ 100 E-MINI Dec26" and "S&P500 EMINI FUT Dec26" (HFEQ-FS, page 1). Five index futures make up 68.65% of the top 10 (my arithmetic).
- Direct shorts, margin type not stated: "the Fund will also “short” the securities of Underlying ETFs" (HFEQ-PR, page 6) and "a Fund will arrange through a broker to borrow the security it does not own" (HFEQ-PR, page 71). No document says Reg T, Regulation T or portfolio margin.
- Swaps left out: the prospectus says "to a lesser extent, swaps" (HFEQ-PR, page 5) but names no swap type or counterparty, and no swap is in the top 10 (my inference). See section 6.
- Leverage cost: no interest or financing figure in the fee table (HFEQ-PR, page 4) or the financial highlights for July 14 to August 31, 2025 (HFEQ-PR, page 86). No annual report for fiscal 2026 was attached.
- Short dividend expense: as above. The SAI says only that "Dividend expenses on securities sold short will be borne by the shareholders of the Funds" (HFEQ-SAI, page 14, "Short Sales").
- Ranking properties (Rank to Score): from the ranking of the 27 LS peers prepared November 11, 2026, using only the project's fund profiles. Each of the seven criteria scores Yes = 1, Partly = 0.5, No or Not stated = 0. Funds sort first by Portfolio margin (YES, LIKELY, POSSIBLE, UNLIKELY, NO), then by Score, then Tidal funds first, then higher gross exposure (my inference).
- Rank: 5 of 27, as of November 11, 2026.
- Long/short: Partly. Long and short positions in broad ETFs and index futures (HFEQ-PR, page 5); 170.0% long and 4.9% short on August 31, 2026 (HFEQ-NP, Part C; my arithmetic).
- Portfolio margin: POSSIBLE. The prospectus describes "Shorting by Borrowing" ETF shares through a broker (HFEQ-PR, page 71), and no document says Reg T or portfolio margin.
- Cross-collateral: Partly. "A Fund will be required to pledge its liquid assets to the broker to secure its performance on short sales" (HFEQ-SAI, page 14). Whether long ETF shares are pledged is not stated.
- Outside Reg T: Not stated.
- Short costs (includes dividends): Not stated. No interest or financing figure appears in the fee table or financial highlights (HFEQ-PR, pages 4 and 86).
- Over 2.0x: No. 1.75x, or 1.82x counting the VIX future, on August 31, 2026 (HFEQ-NP, Part C; my arithmetic).
- Tidal: Tidal Investments LLC is the adviser, and the fund is a series of Tidal Trust I (HFEQ-SAI, page 2, cover).
- Score: 2 (my arithmetic).
16. Fund Documents
Fact Sheet